JAFFNA, Nov. 1: The Ceylon Teachers’ Union on Friday asked Sri Lanka’s anti-corruption commission to investigate Nagalingam Vethanayahan, Governor of the Northern Province. The complaint concerns two development projects carried out while he was Government Agent and District Secretary of Jaffna, the district’s most senior civil servant, from March 2015 to February 2020.
The complaint accuses him of fraud and of buying machinery to collect commissions. As evidence, the union attached two internal audits written in 2020 by K. Kamalaruban, chief internal auditor of the Jaffna District Secretariat. One covers a dairy project and the other a plant to recycle fecal sludge.
Jaffna Monitor compared the union’s three-page complaint, line by line, with the two audits, which run to 15 and seven pages and are written in Tamil. Many of the complaint’s points match the audits closely. On the most serious charges, bribery, fraud and commissions, the complaint goes further than the audits do. The complaint also leaves out several of the audits’ most significant findings.
What an Internal Audit Does
An internal audit is a review carried out by a government office’s own auditor. The auditor checks the office’s files against procurement guidelines and financial regulations, records where the rules were not followed, and reports to the head of the office. An internal audit does not decide whether a crime was committed, and it does not establish who is to blame.
Both audits are addressed to the Government Agent who succeeded Mr. Vethanayahan, and were written a few months after he left the post. They refer to officials by title, such as the Government Agent, the District Secretary and the technical evaluation committee. Neither audit names Mr. Vethanayahan.
The audits use strong language in places. One calls a decision a misuse of government funds, and another, wasteful expenditure. Neither uses the words fraud or bribery, and neither makes any finding about why officials acted as they did.
Where the Complaint and the Audits Agree
On the fecal sludge project, the complaint follows the audit closely, in places almost word for word.
Both documents say the project, planned for Chunnakam, Chavakachcheri and Kapputhu in 2016, began without a feasibility study or environmental approval, and that no engineer qualified in the technology sat on the technical evaluation committee.
Both describe the same sequence of payments in December 2016. The contractor, S.S.R. Construction (Pvt) Ltd, received a 14.5 million rupee advance on Dec. 2. A first part-payment of 9.5 million rupees was claimed on Dec. 22 and paid three days later, without measurement sheets. A third payment of 29.9 million rupees was recorded as paid and spent by Dec. 31. The District Secretary then approved paying that same sum in three later installments.
Both also say that 12.2 million rupees already recorded as spent was moved into the secretariat’s general deposit account without Treasury approval.
Government money allocated for a year generally lapses if it is not spent by Dec. 31. Recording a payment as made before the year ends, and later paying it in installments, keeps the money from lapsing. The financial regulations do not permit this. The audit does not say why it was done.
Where the Complaint Goes Further
On the dairy project, the complaint and the audit differ in what they claim.
The six million rupees. The complaint says more than 6 million rupees was “misappropriated.” The audit records a payment of 6,032,200 rupees to the supplier, Analytical Instruments (Pvt) Ltd, in November 2017. In March and June 2018, the District Secretary wrote to the company that two of the items it had supplied did not meet specifications and asked for replacements. The auditor found no record that they were replaced. The audit says payment was made for goods that did not meet specifications. It does not say the money was stolen or diverted.
Cabinet approval. The complaint says the project went ahead while Cabinet approval had been applied for but not received. The audit says approval was sought and that the auditor could find no letter in the file showing it had been granted. That is a gap in the records. It does not establish that approval was never given.
Commissions and bribery. The complaint says machinery was bought without the details the technical committee had requested, “aiming to receive brokerage commissions to fulfill personal needs,” and that unsuitable machinery was bought “solely for bribery and fraudulent activities.” The audit confirms that the bidders did not supply the details the committee asked for. It contains nothing about commissions or bribes.
Ruined machinery. The complaint says machinery bought before its building was finished was kept in unmaintained places “causing them to perish.” The audit says that as of 2020, equipment worth several million rupees was stored in unsuitable and unsafe places, and it includes photographs. It does not say whether the equipment was damaged.
The complaint also describes the audits as evidence that Mr. Vethanayahan “engaged in financial irregularities and frauds.” The audits describe what the secretariat did. They do not attribute any act to him by name.
What the Complaint Leaves Out
The audits contain findings the complaint does not mention. Some of them are more serious than the points it does raise.
Two reports with the same date. Three companies bid to supply the dairy equipment. On Sept. 27, 2016, the technical evaluation committee recommended a fresh tender, because the bidders had not provided the required details, and rejected Analytical Instruments’ bid, giving its reasons. No fresh tender was called.
The file also holds a second report with the same date, which rejects the other two bidders and selects Analytical Instruments alone. The two reports give different closing dates for the bids. The auditor found that the second report had been filed after a letter dated Oct. 25, 2017, and concluded that it was prepared in 2017 “for improper use.” Analytical Instruments was the most expensive bidder, at 36.8 million rupees before tax, against 32.8 million and 33.6 million from the other two. The auditor found no document justifying the choice.
The Government Agent signed the contract with the company’s chairman on Dec. 15, 2016, requiring delivery by Dec. 31. The equipment arrived 10 months late, and no late-delivery penalty was charged.
A second phase without tenders. In 2018, the secretariat awarded two more contracts on the dairy project, for 39.8 million rupees in machinery and 16.8 million rupees for a building, to a single company, Dairy Machinery Services (Pvt) Ltd, without open tenders. The auditor said this breached national procurement guidelines. Both contracts were signed after the completion dates written into them. One names as its client a “Jaffna District Development Society,” which the auditor said does not exist in Jaffna. In December 2019, a technical committee found that four items the company supplied did not meet specifications.
The audit lists all three dairy contracts as overdue, by 1,245 days, 420 days and 360 days.
A bill that came later. The sludge audit cites a letter from the contractor’s engineer, dated May 4, 2017, saying the bill for the 29.9 million rupee payment had been submitted. The secretariat had approved that payment on Dec. 31, 2016, more than four months earlier. The auditor called this entirely contrary to the financial regulations.
Plants left unfinished. The secretariat terminated the sludge contract in March 2018, after recovering 9.6 million rupees of the advance. Local government bodies refused to take over the half-built plants. The remaining work was then given without a tender to DEC Traders, agent for an Indian company, on an estimate of about 8 million rupees that no engineer recommended and no accounting officer approved.
Who Made the Decisions
The audits show decisions taken at several levels. The Government Agent signed the first dairy contract. The District Secretary approved splitting the 29.9 million rupee payment, on a planning official’s recommendation. Technical committees wrote the evaluation reports, and a planning official proposed the transfer to the deposit account.
The audits do not say who drafted the second evaluation report or who ordered it filed. Who was responsible for each breach, and whether any of them was a crime, is for investigators to decide.
The Union and the Governor
The complaint, dated Oct. 30, is signed by the union’s vice president, A. Theeban Thileeshan, and the commission’s acknowledgment, reference AC/711, is addressed to him. Tamil news sites reported that the union’s general secretary, Joseph Stalin, a veteran trade unionist, submitted it in Colombo. The acknowledgment states that accepting a complaint does not guarantee an investigation.
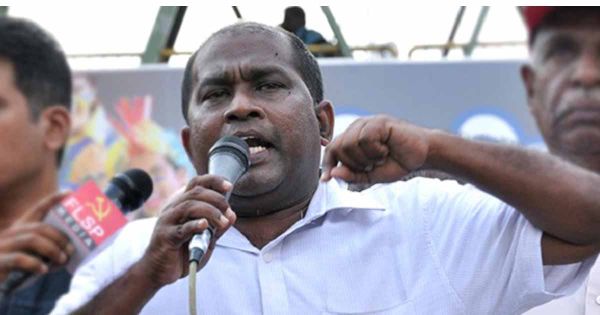
The union and the governor have been in conflict for months over teacher transfers. In March, the union wrote to the President and the Prime Minister alleging irregularities in transfers made on grounds of service need. The governor’s office has said the union withdrew from the provincial transfer board after its representative refused to accept a board decision. In April, Mr. Thileeshan told reporters that the governor should resign and that otherwise the union would expose his irregularities.
In March, a member of the Velanai Pradeshiya Sabha, Swaminathan Pirahalathan, separately complained to the Financial Crimes Investigation Division about a 77 million rupee ecotourism project begun in 2016 on Mandaitivu. That complaint named Mr. Vethanayahan and two former Velanai divisional secretaries.
President Anura Kumara Dissanayake appointed Mr. Vethanayahan governor in September 2024. As governor, he has removed two local council leaders by gazette after official inquiries into alleged irregularities. A court later suspended one of those removals.
Stamps on the audits show that the District Planning Secretariat received them in July and September 2020. Jaffna Monitor could not establish what action, if any, followed. The commission has not said whether it will investigate.